Anthropic compute margins worsen despite expectations
TechCrunch reports that Anthropic's compute margins are worsening, contrary to expectations that they would improve. The report highlights ongoing economic challenges in AI compute for the company.
Coverage timeline
TechCrunch AIRussell Brandom
At a moment when Anthropic's compute margins should be getting better, they’re getting worse.
Related stories
Anthropic files S-1 for Nasdaq IPO under ticker ANT
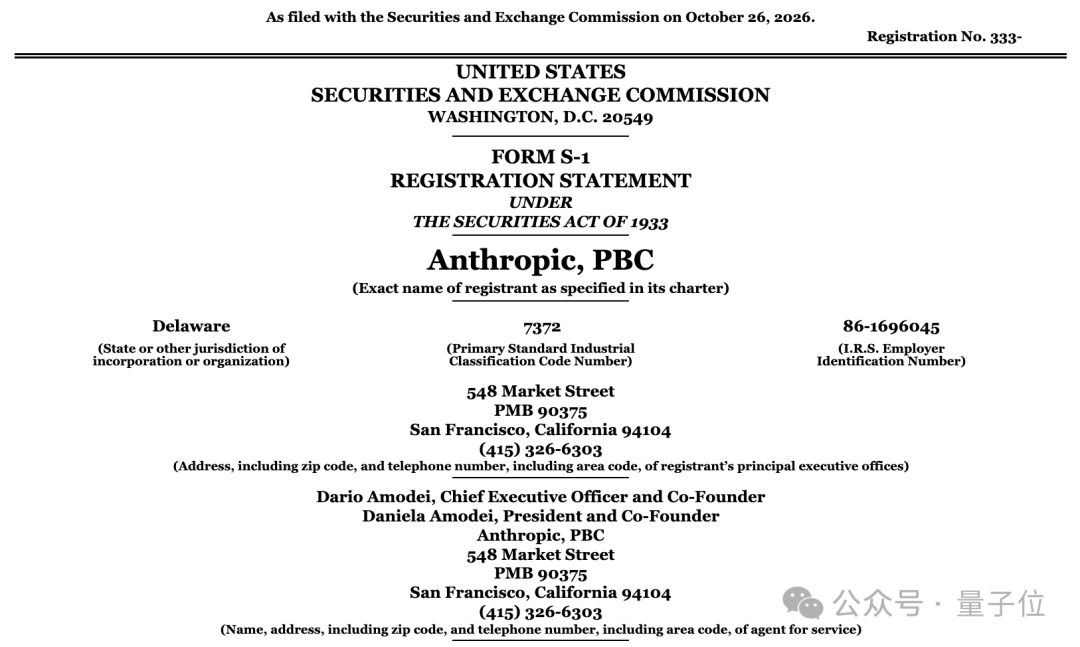
Anthropic publicly filed its S-1 registration statement with the SEC on October 26, 2026, for a proposed initial public offering on the Nasdaq under the ticker symbol ANT. The filing reveals strong revenue growth, mounting losses, an unusual governance structure for founder control, and significant compute commitments, with the number of Class A shares and price range yet to be determined.
32 reports · 8 sources1703 points · 1674 comments
Anthropic faces cloud compute shortages ahead of November IPO
Anthropic is reportedly struggling to secure sufficient compute from cloud providers that increasingly view it as a competitor, according to a TechCrunch report dated October 20, 2026. This challenge comes as its infrastructure spending escalates ahead of a planned November IPO.
Anthropic S-1: $80.7B H1 net loss, $16.3B revenue, $782B lease obligations
Anthropic filed its S-1 prospectus with the SEC, reporting an $80.7B net loss on $16.3B revenue in H1 2026, up from a $13B loss on $1.2B revenue in H1 2025. The filing reveals nearly $9B in computing infrastructure costs, $782B in lease obligations, and 94 pages of risk factors, including warnings about catastrophic AI incidents and potential targeting by the Trump administration. The company plans to list on Nasdaq under the ticker 'ANT'.
7 reports · 2 sources

Anthropic IPO prospectus: H1 2026 revenue $16.3B, net loss $80.7B
Anthropic's draft IPO prospectus, viewed by the Wall Street Journal, discloses H1 2026 revenue of $16.3 billion, up from $1.1 billion in H1 2025, with about 20% of revenue coming from two customers. The document also reports an $80.7 billion net loss for the period, driven by accounting charges, and lists a long set of risk factors.
2 reports · 2 sources190 points · 100 comments
News updates every hour. Subscribe in your RSS reader to get new stories automatically.
Subscribe